Problems we solve

Payroll week shouldn't feel like a countdown.

Profitable on paper, broke in the bank — we hear it in almost these exact words from owners of businesses that are, by every other measure, succeeding. Cash pressure has mechanics: timing, collections, margin, and visibility. Fix the mechanics and the fear goes with them. We've done it inside hundreds of companies.

Confidential, owner-to-owner, and specific to your numbers.

300+businesses served nationwide
Top 1%consultant recognition
2×1written net-profit guarantee
The short answer: Cash flow problems usually come from timing and margin, not from a lack of sales — money goes out for payroll and materials weeks before invoices are collected, and each job keeps too little to refill the gap. The fix, in order: build a 13-week cash forecast from real receivables and payables, install a weekly collections and payables rhythm, then repair pricing so every job deposits more than it drains. Borrowing before fixing those mechanics only rents time — the gap comes back with interest attached.
Sound familiar?

The bank balance runs your day

Cash pressure doesn't show up in the annual statements. It shows up at 6 a.m., in the gap between the balance on the screen and the checks you know are about to hit.

  • You check the bank balance before you check your email
  • Customers pay whenever they pay; payroll never waits
  • The P&L says profit — the account says otherwise
  • You've timed vendor checks against a deposit you hoped would clear first
  • Growth makes it worse: every new job swallows cash before it returns any
  • You've stopped taking distributions so the company can breathe

Two neighbors of this problem are worth ruling out early. If the losses are real and not just timing, start at business losing money. If the bank account is thin because every job keeps too little, the root is margin, not timing — and the treatment is different.
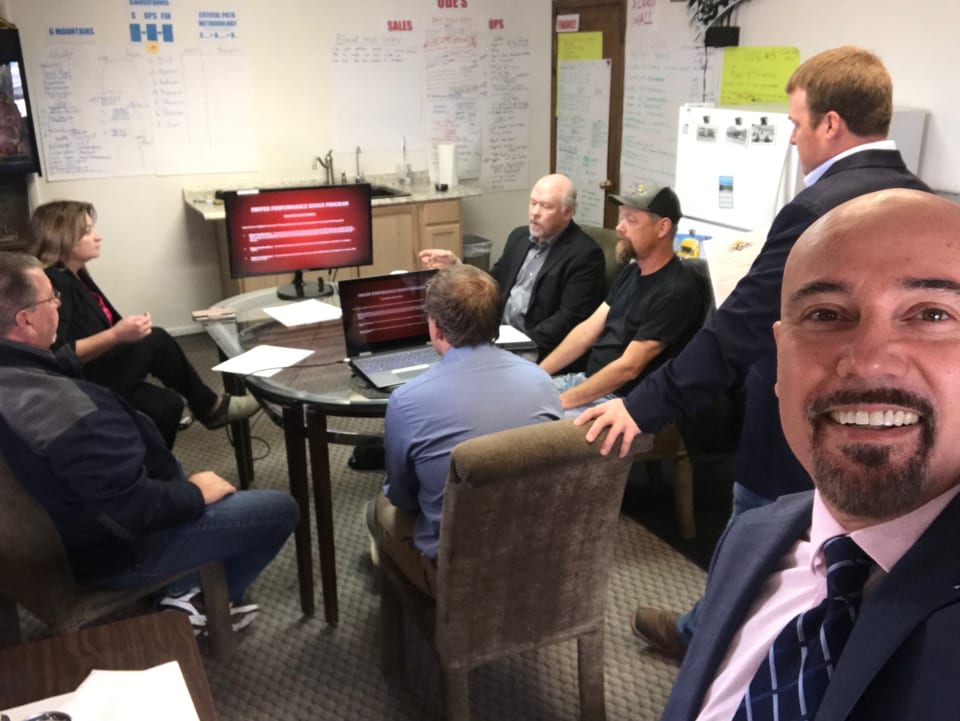
Armando Juarez presenting an incentive program in a client working sessionArmando on site

Armando presenting a driver bonus program to a client's team.

How we fix it

Replace the scramble with a system

See 13 weeks ahead

The first deliverable is a 13-week cash view built from your real receivables, payables, and payroll calendar — the same instrument our turnaround engagements open with. Surprises become line items you saw coming a month out, which changes every decision you make.

Build the collections & payables rhythm

Then cash gets managed on a weekly cadence: invoices out the day work completes, receivables worked on a schedule instead of when things get scary, vendor terms negotiated deliberately. We install it as documented routines your office runs — at Northern Tier Transportation, cash management reporting ran alongside weekly management meetings as part of one engagement.

Repair margin and pricing

Timing discipline manages cash; only margin creates it. The lasting fix is profit improvement — job costing, corrected pricing, and plugged leaks — so each job deposits more than it drains and the pressure stops regenerating every month.

$847K
“The amount of money losses and missed opportunities that Mr. Juárez identified in our company totaled approximately $847,000 — with a projected recovery over 12 months.”
American Oil CompanyTurnaround engagement
The cost of waiting

What one more scrambling quarter actually costs

The trough deepens as you grow

Every new job buys labor and materials weeks before its invoice comes back, so the busier the quarter, the wider the gap between cash out and cash in. Waiting doesn't hold the problem steady — winning more work makes payroll week harder, which is the cruelest version of success there is.

Rented time gets expensive

A credit line drawn to cover a recurring gap doesn't close the gap — it adds interest to it, and it spends the cushion you'll want for a real emergency. Borrowing against an unfixed timing problem gradually converts it into a debt problem, which is a harder one to walk back.

Panic starts pricing your decisions

Discounts offered just to get paid faster, bad-fit work taken for the deposit, vendor checks timed against a deposit you hoped would clear — decisions made from a low balance routinely cost more than the gap itself. A 13-week view exists precisely so choices get made a month early, calmly.

Cash flow FAQ

Asked in almost every first call

How can the business be profitable and still run out of cash?
Because profit is an opinion about a period and cash is a fact on a date. Revenue booked isn't collected; materials and payroll go out weeks before the invoice comes back in. The faster you grow, the wider that gap gets. That's why the 13-week view comes first — it shows the gap instead of letting you feel it.
Should I just borrow to cover the gap?
Borrowing buys time; it doesn't fix mechanics. If collections, terms, and margins stay as they are, the line gets drawn down again and now carries interest. The order matters: understand the gap, fix what creates it, and then borrowing — if still needed — becomes a bridge with a far side instead of a habit.
What actually changes in the first month?
Typically: a working 13-week forecast, a triaged payables plan, collections moving on the oldest receivables, and a payroll week you walked into knowing the number in advance. If that sounds like relief, request a confidential assessment — it costs nothing to find out what your version looks like.
How fast can cash flow problems be fixed?
Visibility comes first and comes quickly: a 13-week cash forecast is built from your real receivables, payables, and payroll calendar, so the guessing typically ends within the opening weeks of an engagement. The structural fix — collections rhythm, negotiated terms, repaired margins — takes longer, because it changes how the company operates rather than just what it can see. In practice the panic usually ends well before the problem does, since knowing the number a month early removes most of the fear. How the engagement runs, step by step.
Should I take a loan to cover payroll?
Treat that question as a flashing warning light, not a routine financing decision. A loan can responsibly bridge a genuine one-time timing gap — but if the gap is created by slow collections or thin margins, it will reopen next month with interest now attached. Before borrowing, get the 13-week view built so you know whether you're bridging to a far side or just delaying the same shortfall. That discipline is where our turnaround work begins, and it has changed more than one borrowing decision.
How do I get customers to pay their invoices faster?
Systematize collections instead of personalizing them: invoice the same day work completes, put terms on every invoice, and work receivables on a fixed weekly schedule rather than whenever the balance gets scary. Most late payment is drift, not refusal — customers reliably pay the vendors who follow up predictably, and drift goes to whoever doesn't. A customer who only pays under pressure is also telling you something about pricing and selection. We install this as documented routines your office runs without you chasing anyone.
What is a 13-week cash flow forecast and why does my business need one?
It's a week-by-week projection of every dollar expected in and out — receivables, payables, payroll, taxes — covering the next quarter, and it gets rebuilt from actuals every week so it stays honest. Thirteen weeks is long enough to see a payroll crunch or tax date coming and short enough to stay concrete. It's the first deliverable in our engagements because it converts dread into line items you can act on a month in advance. The full method is in the Owner's Guide to Cash Flow Management.
Related insights

Guides for tight weeks

Every dollar you invest returns at least two in net profit. Guaranteed.

That is our 2×1 guarantee. Complete the short qualifying application and get a free, no-obligation business assessment with an accredited consultant.

Start your free assessment